The Hidden Costs: How Social Polarization Impacts Your Household Budget in 2026
In an increasingly interconnected yet paradoxically divided world, the concept of social polarization has moved beyond academic discourse to become a tangible force shaping our daily lives. While often discussed in political or cultural terms, its economic ramifications are profound, particularly when examining the direct impact on household budgets. As we navigate 2026, understanding how social polarization financial impact manifests is crucial for every family striving for economic stability.
The divisions we witness in society, whether ideological, political, or cultural, are not confined to the realm of public debate. They seep into economic systems, influencing everything from consumer confidence and market stability to policy-making and international trade. For the average household, this translates into a complex web of challenges, often manifesting as unexpected expenses, reduced opportunities, and an overall increase in the cost of living. This article delves deep into these hidden costs, exploring the intricate ways social divides are quietly eroding your financial well-being and offering insights into navigating this challenging landscape.
Understanding Social Polarization and Its Economic Roots
Before we dissect the financial fallout, it’s essential to define what we mean by social polarization. It’s not merely disagreement; it’s a profound divergence of attitudes, beliefs, and values within a society, leading to the formation of distinct, often antagonistic, groups. This divergence can be fueled by various factors, including economic inequality, technological disruption, political rhetoric, and media consumption patterns. When these divides harden, they create friction that can impede collective action and efficient resource allocation, both vital for a healthy economy.
Economically, polarization often stems from or exacerbates disparities in wealth, income, and opportunity. When certain segments of society feel left behind or perceive that the system is rigged against them, it fosters resentment and distrust. This can lead to calls for protectionist policies, increased regulation, or even radical shifts in economic models, all of which introduce uncertainty and can deter investment. The cycle is self-reinforcing: economic grievances fuel social divides, which in turn create economic instability, further deepening the divides. This reciprocal relationship makes the social polarization financial impact particularly insidious and difficult to address.
The rise of the digital age has also played a significant role. Echo chambers created by social media algorithms and partisan news outlets amplify existing divisions, making it harder for people to engage in constructive dialogue or find common ground. This lack of consensus can paralyze political processes, delaying crucial economic reforms or infrastructure projects that could otherwise boost productivity and create jobs. The long-term consequences of such paralysis are borne by everyone, but disproportionately affect those with fewer resources.
Consider, for instance, the impact on labor markets. When there’s a strong divide between different sectors or skill levels, it can hinder the mobility of labor and the efficient matching of workers to jobs. This can lead to persistent unemployment in some areas while others face labor shortages, creating inefficiencies that ripple through the entire economy and ultimately affect consumer prices and wages. Furthermore, a polarized society may struggle to invest in education and training programs that are universally beneficial, instead focusing on narrow interests or ideological priorities. This underinvestment in human capital can stifle innovation and long-term economic growth, impacting future generations’ earning potential and overall prosperity.
Market Instability and Investment Uncertainty
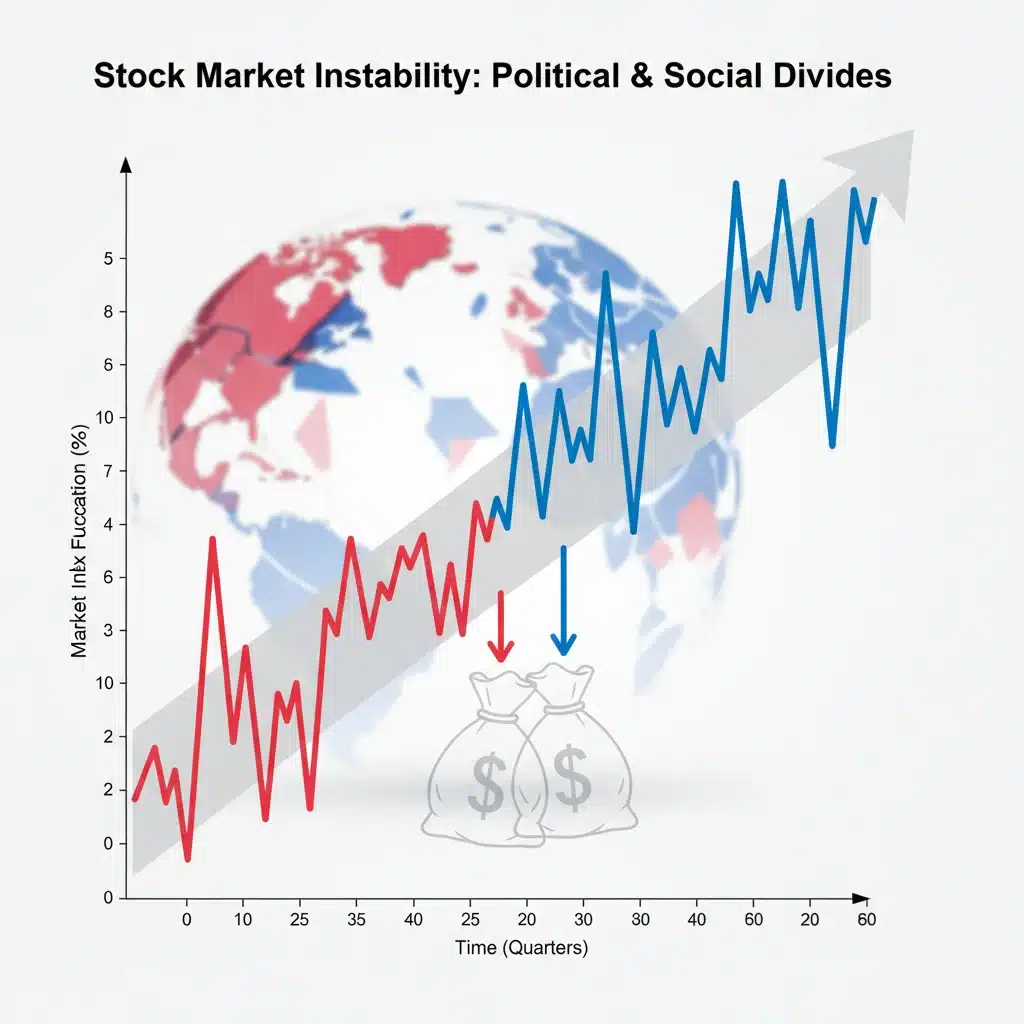
One of the most immediate and visible consequences of social polarization is its effect on financial markets. Uncertainty, whether political or social, is anathema to investors. When there’s a lack of predictability regarding future policies, regulatory environments, or even social cohesion, capital tends to become risk-averse. This can lead to increased market volatility, making it harder for businesses to plan and invest, and for individuals to save and grow their wealth.
Consider how political gridlock, a direct outcome of deep polarization, can delay budget approvals, debt ceiling debates, or critical economic legislation. Each instance introduces a period of heightened uncertainty that can send shockwaves through stock markets, bond markets, and currency exchanges. Businesses, facing an unpredictable regulatory landscape or potential shifts in trade policy, may postpone expansion plans, reduce hiring, or even relocate operations to more stable environments. This reduction in economic activity directly translates to fewer job opportunities, slower wage growth, and diminished returns on investments for households.
Moreover, social polarization can manifest in consumer behavior. Boycotts, protests, and shifts in brand loyalty based on perceived political alignment can create significant challenges for companies, forcing them to navigate a minefield of public opinion. This can divert resources from innovation and product development towards managing reputation and political risk, ultimately impacting their profitability and their ability to offer competitive prices or wages. The aggregate effect of these individual business decisions contributes to a less dynamic and less resilient economy, increasing the overall social polarization financial impact.
For individual investors, market instability means greater risk and potentially lower returns. Retirement savings, managed through pension funds or individual investment accounts, are exposed to these fluctuations. The need for greater diversification or more conservative investment strategies might reduce potential gains over the long term. Furthermore, heightened uncertainty can lead to ‘flight to safety’ phenomena, where investors flock to traditionally stable assets, distorting their true value and potentially creating asset bubbles that could burst, causing further economic disruption. This constant state of vigilance and adjustment places an additional burden on households trying to secure their financial future.
Rising Cost of Living and Inflationary Pressures
Perhaps the most direct way social polarization financial impact hits household budgets is through an increase in the cost of living. This can happen through several mechanisms, often intertwined with the market instability discussed above.
Firstly, political and social divisions can impede efficient supply chains. For example, if trade relations become strained due to geopolitical polarization, tariffs or trade barriers can be imposed, increasing the cost of imported goods. Even domestic supply chains can be affected if labor disputes or regulatory disagreements, often fueled by ideological differences, disrupt production or transportation. These inefficiencies inevitably translate into higher prices for consumers, from groceries to electronics.
Secondly, polarization can undermine effective policy responses to inflation. When political factions cannot agree on fiscal or monetary policies, the government’s ability to stabilize prices is severely hampered. Delays in adjusting interest rates, approving targeted subsidies, or implementing long-term economic strategies can allow inflationary pressures to spiral out of control. This erosion of purchasing power means that every dollar a household earns buys less, effectively reducing their real income.
Consider the energy sector. Disagreements over climate policy, fossil fuel production, and renewable energy mandates can lead to inconsistent energy policies. This inconsistency can deter investment in new energy infrastructure, leading to supply shortages and volatile energy prices. For households, this means higher utility bills, more expensive gasoline, and increased costs for any goods or services that rely heavily on energy for production or transport. These are not minor fluctuations; they are systemic increases that can significantly strain a family’s budget, especially those with fixed incomes or limited savings.
Furthermore, social polarization can lead to a decline in public trust and social capital. When communities are deeply divided, it can be harder to mobilize collective action for local economic development, infrastructure improvements, or shared social services. This can result in a deterioration of public goods, forcing households to spend more on private alternatives (e.g., private security instead of effective public safety, private schools instead of well-funded public education), thereby increasing their overall expenditures. The cumulative effect of these factors creates a persistent upward pressure on the cost of living, making it increasingly difficult for households to maintain their standard of living.
Impact on Public Services and Social Safety Nets
A less obvious but equally damaging consequence of social polarization financial impact is the erosion of public services and social safety nets. When society is deeply divided, reaching a consensus on funding essential services like education, healthcare, infrastructure, and social welfare programs becomes incredibly challenging.
Political polarization often leads to legislative gridlock, preventing the passage of budgets that adequately fund these crucial services. Different factions may prioritize vastly different areas, leading to stalemates or short-term funding solutions that lack the stability needed for long-term planning and improvement. For example, debates over healthcare reform, often highly polarized, can leave millions without affordable access, forcing households to bear higher out-of-pocket costs or face financial ruin due to medical emergencies. Similarly, underfunded public education systems can compel families to seek expensive private alternatives or settle for substandard educational outcomes, thereby limiting their children’s future economic prospects.
Infrastructure is another critical area. Roads, bridges, public transportation, and digital networks are the backbone of a modern economy. When investments in these areas are delayed or insufficient due to political infighting, it leads to inefficiencies that affect everyone. Businesses face higher transportation costs, commuters spend more time and money on travel, and the overall productivity of the economy suffers. These costs are eventually passed on to consumers or result in reduced wages, hitting household budgets from multiple angles.
Moreover, social safety nets, designed to protect the most vulnerable during economic downturns or personal crises, can be weakened by polarization. Debates over the scope and funding of unemployment benefits, housing assistance, or food programs can lead to cuts or inadequate provisions. This means that when households face unexpected financial shocks – job loss, illness, or natural disaster – they have fewer resources to rely on, increasing their risk of poverty and long-term financial instability. The increasing cost of living combined with a weakening safety net creates a precarious situation for many families, highlighting the profound social polarization financial impact.
Erosion of Trust and Transaction Costs
Trust is an invisible yet incredibly powerful lubricant for economic activity. When social polarization erodes trust – between citizens and institutions, between businesses and consumers, and even within communities – it introduces ‘transaction costs’ that would otherwise not exist. These costs, while not always immediately apparent, collectively add up and negatively impact household finances.
Consider the legal system. A polarized society might see an increase in litigation, as parties are less willing to compromise and more prone to seeking adversarial solutions. This drives up legal costs for businesses, which are then passed on to consumers through higher prices. Similarly, a decline in trust in government institutions can lead to increased regulatory burdens, as governments try to compensate for perceived lack of compliance or fairness. These regulations, while sometimes necessary, can add to the cost of doing business, again impacting consumer prices and economic efficiency.
In the private sector, businesses operate more efficiently when there is a baseline of trust. Supply chain partners trust each other to deliver on contracts, employers trust employees to perform their duties, and consumers trust businesses to provide quality goods and services. When this trust breaks down due to social divisions, businesses may have to implement more stringent and costly oversight mechanisms, or they may face increased risks of fraud or non-compliance. These additional costs ultimately find their way into the price of goods and services, silently chipping away at household purchasing power. The social polarization financial impact here is subtle but pervasive.
Furthermore, the erosion of trust can hinder innovation and collaboration. Scientific research, technological development, and entrepreneurial ventures often rely on diverse groups of people working together, sharing ideas, and building on each other’s strengths. If social divides create barriers to such collaboration, it can slow down progress and reduce the creation of new economic opportunities. This long-term stagnation means fewer high-paying jobs and less economic dynamism, ultimately limiting the financial growth potential for households across the spectrum. The social cost of distrust translates directly into an economic burden.
Strategies for Households to Mitigate Financial Strain
While the broader forces of social polarization financial impact might seem overwhelming, individual households are not entirely powerless. There are strategies you can employ to mitigate some of the financial strain and build resilience in an uncertain economic climate.
1. Diversify Investments and Savings: In times of market instability, diversification is key. Don’t put all your eggs in one basket. Spread your investments across different asset classes (stocks, bonds, real estate, commodities) and geographies to reduce risk. Consider consulting a financial advisor to tailor a strategy that aligns with your risk tolerance and financial goals, especially given the unpredictable nature of markets influenced by social divides. Having an emergency fund, readily accessible, is also more critical than ever to weather unexpected financial shocks.
2. Focus on Essential Spending and Frugality: With rising inflation and cost of living, re-evaluating your spending habits is paramount. Create a detailed budget, identify non-essential expenses, and look for areas to cut back. This might involve meal planning to reduce food waste, seeking out cheaper alternatives for everyday items, or reducing discretionary spending on entertainment and luxury goods. Every saving, however small, contributes to financial resilience against the backdrop of increasing costs.
3. Enhance Skills and Adapt to Changing Job Markets: Economic polarization can lead to shifts in demand for certain skills. Invest in continuous learning and skill development to remain competitive in the job market. This might involve online courses, certifications, or even pursuing higher education in fields that are projected to grow. A strong, adaptable skill set provides better job security and opportunities for wage growth, counteracting the negative effects of economic uncertainty caused by social divides. Networking and staying informed about industry trends can also open doors to new opportunities.
4. Advocate for Local and Community Solutions: While national-level polarization can be frustrating, focus on what you can influence locally. Support local businesses, participate in community initiatives, and advocate for policies that promote local economic growth and social cohesion. Strong local economies can offer a buffer against national economic turbulence and foster a sense of shared purpose that mitigates some of the negative effects of broader social divides. Community-supported agriculture, local co-ops, and neighborhood watch programs are examples of how collective action can improve local living standards and reduce costs.
5. Stay Informed, Not Overwhelmed: Being aware of economic trends and policy discussions is important, but it’s equally crucial to avoid being overwhelmed by constant negative news. Seek out reliable, diverse sources of information to understand the complexities without succumbing to sensationalism. Informed decision-making, rather than panic, is your best defense against the financial implications of social polarization. Understanding the underlying causes of economic shifts can help you make more proactive and strategic financial choices for your household.
6. Build Strong Financial Literacy: The more you understand about personal finance, investing, and economic principles, the better equipped you will be to navigate challenging times. Resources are abundant, from online courses to books and workshops. Learning how to manage debt, understand credit scores, and plan for retirement are foundational skills that become even more valuable when economic conditions are turbulent due to societal friction. This empowers you to take control of your financial destiny rather than feeling like a victim of external forces.
7. Consider Alternative Income Streams: In an era of economic uncertainty, relying solely on one income source can be risky. Explore opportunities for side hustles, freelancing, or developing passive income streams. This diversification of income can provide a crucial safety net if your primary employment is impacted by economic downturns or industry shifts exacerbated by social polarization. The gig economy, while having its own challenges, also offers flexibility for those looking to supplement their income and enhance their financial security.
8. Engage in Constructive Dialogue: While not a direct financial strategy, fostering understanding and reducing polarization in your personal spheres can have a ripple effect. Engaging in respectful conversations, seeking common ground, and promoting empathy can contribute to a more cohesive society which, in the long run, supports a more stable economic environment. A less polarized society is a more economically efficient society, and this ultimately benefits every household.
The Long-Term Economic Outlook and Your Household
The long-term economic outlook is inextricably linked to the trajectory of social polarization. If divisions deepen, the cumulative social polarization financial impact could lead to sustained periods of lower economic growth, higher inflation, and greater inequality. This scenario would make it increasingly difficult for households to accumulate wealth, save for retirement, or provide for future generations. The intergenerational transfer of wealth could be severely hampered, perpetuating cycles of economic disadvantage.
Conversely, if societies find ways to bridge divides, foster greater understanding, and achieve consensus on critical economic policies, the potential for robust and inclusive growth is significant. A cohesive society is better positioned to invest in innovation, adapt to global challenges, and create a stable environment for businesses and individuals to thrive. This would translate into more job opportunities, higher wages, more affordable goods and services, and stronger social safety nets, all of which directly benefit household budgets.
For your household in 2026 and beyond, this means that your financial well-being is not solely dependent on your individual efforts, but also on the collective health of society. Being aware of the economic consequences of polarization, and actively engaging in strategies to mitigate its effects, both personally and communally, becomes a form of financial prudence. It’s about recognizing that a stable society is a prerequisite for a stable economy, and by extension, stable household finances. The choices made today, both individually and collectively, will determine the economic landscape of tomorrow.
Conclusion: Navigating a Divided Economic Landscape
The social polarization financial impact is a complex, multi-faceted challenge that extends far beyond political headlines, directly affecting the wallets and well-being of households in 2026. From market instability and rising inflation to the erosion of vital public services and the hidden costs of distrust, the economic consequences of societal divides are profound and pervasive. It’s a silent tax on every family, making it harder to save, invest, and maintain a reasonable standard of living.
However, understanding these challenges is the first step towards resilience. By adopting proactive financial strategies such as diversifying investments, focusing on essential spending, continuously enhancing skills, and engaging in community-level solutions, households can build stronger defenses against economic headwinds. Moreover, recognizing the interconnectedness of societal health and economic prosperity encourages a broader perspective – one where fostering unity and constructive dialogue is not just a social ideal, but an economic imperative.
As we move forward, the ability of societies to address and overcome polarization will be a critical determinant of economic stability and growth. For individual households, navigating this divided economic landscape requires a combination of astute financial planning, continuous adaptation, and an active commitment to fostering a more cohesive and prosperous future for all. Your financial future, in many ways, depends on it.